Which Brevard County Homes Make Sense for Buyers Who Want a Pool but Need Low Insurance Friction?
By Carrie Liotta, Space Coast REALTOR® with REAL Broker | Published August 8, 2026
If you want a pool home in Brevard County but you also need a smoother insurance path, do not shop by the pool first. Shop by the house file first. The best fit is usually a concrete block or well-documented home with a newer roof, clean four-point items, good drainage, permitted pool and screen-enclosure records, safe barriers, and a quote your insurance agent has reviewed before the inspection window closes.
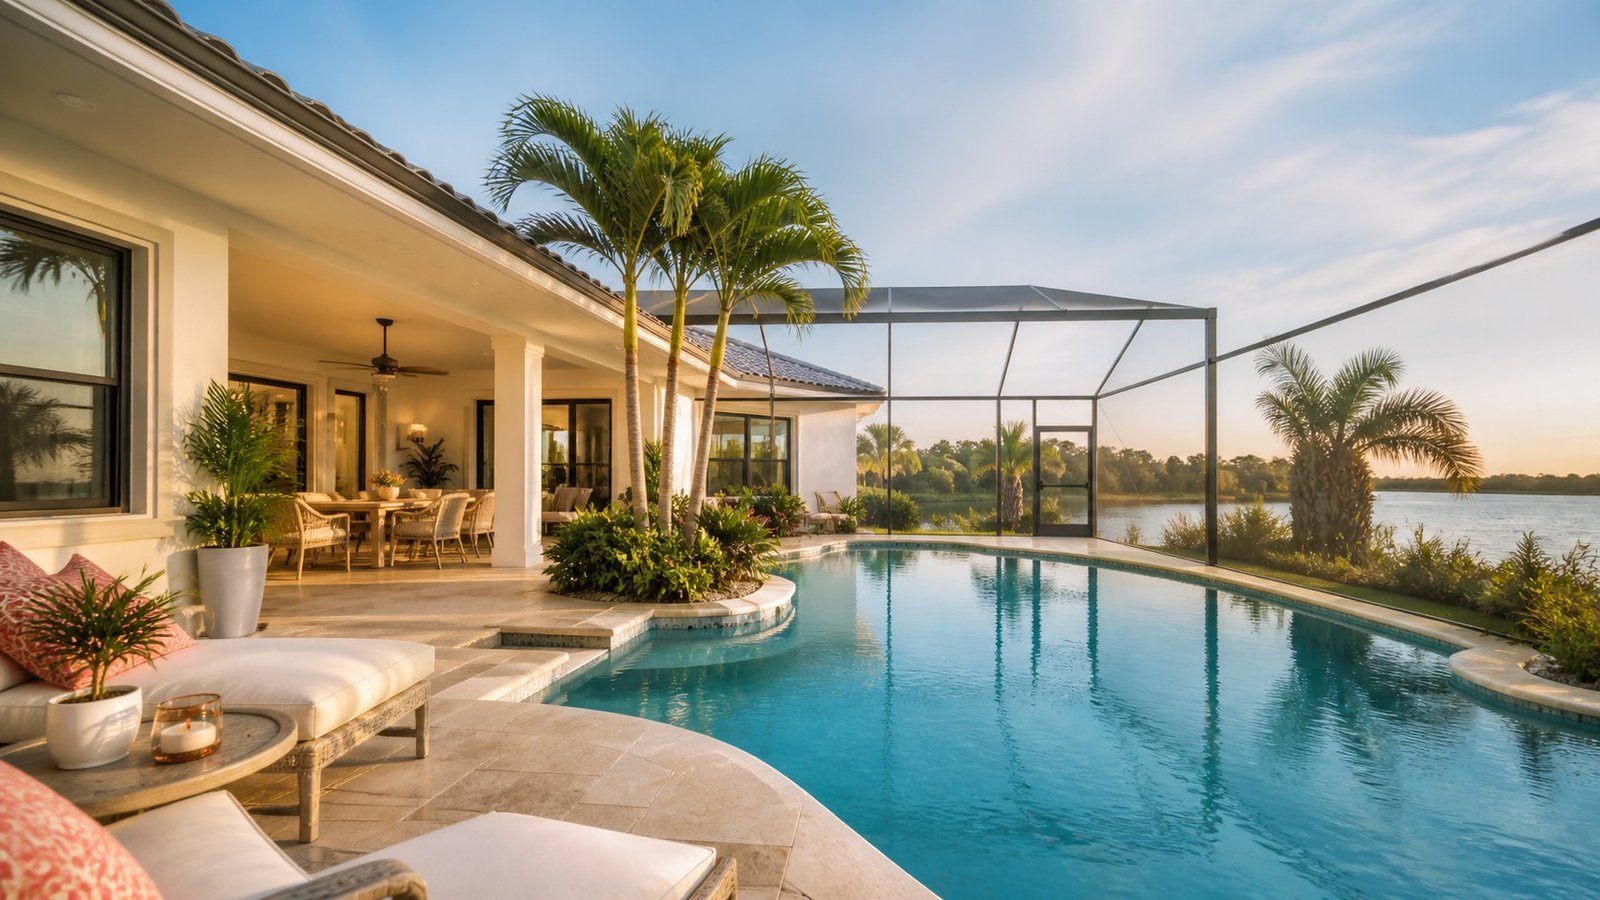
That answer may sound less romantic than “find the prettiest backyard,” but it is the way I protect buyers here. A screened pool can be one of the best parts of Space Coast living. It gives families an easy weekend, makes summer afternoons feel more livable, and gives visiting grandparents or out-of-state friends a reason to linger after beach mornings. But a pool should add joy to the home, not become the feature that distracts you from an aging roof, missing permits, drainage issues, or a fragile monthly payment.
When my clients ask whether they should buy a pool home, I usually ask a better question back: “Can we make the pool make sense after we look at insurance, roof age, storm preparation, safety, and maintenance together?” If the answer is yes, wonderful. If the answer is no, I would rather help you choose a simpler yard now than watch a beautiful pool turn into buyer remorse later.
Start with the roof and four-point picture, not the waterline
In Florida, the roof, electrical, plumbing, and HVAC systems can shape whether an older home feels easy or stressful to insure. That is why a pool home with a sparkling backyard can still be the wrong buy if the roof is near the end of its useful life or the electrical panel, plumbing, or air conditioner raise underwriting concerns.
The Florida Department of Financial Services keeps a consumer summary of Florida property insurance changes, including roof-related reforms that buyers often hear about during the shopping process. Those rules are useful background, but they do not eliminate the need for a property-specific quote. Condition, documentation, carrier guidelines, roof shape, age, prior claims, and the rest of the home still matter.
For pool-home buyers, this matters because the pool often competes with the roof in the budget. A buyer may be tempted to accept a weaker roof file because the backyard feels like the dream. I want you to slow down there. A pool is a lifestyle feature. The roof and major systems are the foundation of your ownership plan.
If you are comparing older resale homes in Suntree, Rockledge, Melbourne, Merritt Island, Cocoa, Titusville, or established Palm Bay neighborhoods, read my guide to Brevard County four-point inspections before making an offer. The same questions apply here, with the pool layered on top.
The lowest-friction pool homes usually have documentation
A pool home becomes easier to evaluate when the seller can produce records. I like to see permits for the pool, screen enclosure, roof, electrical work tied to pool equipment, major resurfacing, and any structural enclosure repairs. I also want service records for the pump, filter, heater if there is one, salt system if installed, and recent leak or resurfacing work.
In Brevard County, the building permit search can be a starting point for county permit history, although homes inside municipalities may have city records and older records may not be complete. A missing permit record is not always a deal-breaker, but it changes how careful we need to be during due diligence.
For example, a 1990s pool home with a newer permitted roof, a serviced HVAC system, a recent pool resurfacing invoice, and a screen enclosure repair record tells a very different story from a similar home where no one can explain when the pool was resurfaced, whether the enclosure was repaired after a storm, or who handled the electrical work around the pump. The first home gives your insurance agent, inspector, and lender something concrete to work with. The second home leaves too much to guesswork.
Good paperwork does not make a bad house good. It simply reduces uncertainty. In this market, reducing uncertainty is valuable.
Look closely at the screen enclosure
Many Brevard buyers picture the classic screened pool: shaded lanai, room for a table, palms beyond the enclosure, and an easy place to rinse off after the beach. I love that setup when the enclosure is solid. But buyers should treat the cage as its own inspection item, not just background scenery.
Ask about age, storm repairs, missing screws, corrosion, screen panel condition, door latches, drainage at the base, and whether any work was permitted when required. A tired enclosure can become a meaningful near-term expense. It can also affect how confident a buyer feels about the home’s storm-readiness story, especially in beachside, river-adjacent, or open-exposure locations.
This is where wind mitigation and opening protection matter too. The Florida Office of Insurance Regulation has wind mitigation resources that explain how certain construction features may relate to insurance discounts. A pool cage is not the same as impact windows or a newer roof, of course, but the broader point is the same: document the home’s storm-resistant features and make sure your quote reflects the actual property, not listing language.
Drainage is a pool-home issue
Drainage deserves more attention than it gets. A pool deck that sends water toward the house, a yard that stays soggy after heavy rain, or a low side yard where equipment sits in poor drainage can turn a pretty backyard into a maintenance problem.
When I walk a pool home with buyers, I look at the slope from the lanai, the location of downspouts, whether the deck has settlement cracks, how the screen enclosure base meets the patio, and whether neighboring lots drain toward the property. After a summer storm, I want buyers to notice where water collects. That is especially important in older Melbourne, Rockledge, Cocoa, Merritt Island, and Palm Bay areas where lot grading varies widely from street to street.
Drainage also ties back to insurance comfort because the same home can have multiple layers of risk. A pool, older roof, weak drainage, mature trees over the enclosure, and limited records can be too much at once. A pool, newer roof, clean yard grading, healthy enclosure, and clear records can feel like a completely different purchase.
Do not skip the safety conversation
Florida has residential swimming pool safety requirements, and buyers should understand them before closing. Florida Statute 515.27 addresses required safety features for residential swimming pools, such as barriers, approved covers, alarms, self-closing doors, or other listed protections depending on the situation.
For a buyer, this is not just a legal footnote. It is practical ownership. If you have young children, visiting grandchildren, pets, or frequent guests, pool safety affects your daily life immediately. Confirm fencing, door alarms, gates, locks, enclosure doors, and any child-safety features during the inspection period. Do not assume that because a pool exists, every safety feature is current, working, or sufficient for your household.
This is also a good time to ask your insurance agent whether the pool configuration, diving board, slide, enclosure, fence, or short-term guest use affects coverage. The answer can vary, and I want that answer before you waive contingencies.
Which Brevard areas tend to fit this buyer?
If your priority is a pool plus lower insurance friction, I usually start with homes that are inland enough to avoid the most expensive flood and wind concerns, but still close enough to the lifestyle you want. That can include parts of Viera, Suntree, Rockledge, West Melbourne, mainland Melbourne, certain Palm Bay pockets with public utilities and good access, and well-documented Merritt Island or Cocoa homes that are not direct waterfront.
Beachside pool homes can absolutely be worth considering, especially if the roof, openings, elevation, and insurance file are strong. But if the monthly payment is already tight, I would be careful about letting a beachside pool stretch every part of the budget. In that case, a mainland pool home with easier access to Pineda Causeway, Eau Gallie Causeway, or 520 may give you the swim-at-home lifestyle without the same carrying-cost pressure.
I recently wrote about choosing a pool home versus prioritizing lower insurance and maintenance costs. This article is the narrower version of that decision: if you still want the pool, choose the home where the rest of the file supports it.
My pool-home checklist before making an offer
Before writing, I want buyers to gather answers in five categories.
- Insurance: early quote, roof age, wind mitigation report, flood zone check, and any pool-specific coverage questions.
- Permits and records: pool permit, roof permit, enclosure permit or repair record, electrical work, resurfacing, equipment replacement, and service history.
- Inspection items: pool shell, tile, coping, deck, enclosure, pump, filter, heater, leaks, bonding, lights, gates, and drainage.
- Safety: barriers, alarms, self-closing gates, locks, door access, and household-specific child or guest concerns.
- Monthly comfort: pool service, chemicals, repairs, electric use, landscaping, insurance, HOA rules, and reserve savings after closing.
That last category is important. A buyer who can afford the payment but has no room for a pump replacement, screen repair, or surprise insurance increase is not really comfortable. The best pool home is not the one with the prettiest listing photo. It is the one you can enjoy after closing without feeling like every maintenance item is an emergency.
“Carrie was an absolute gem! She helped me and my husband look for houses off and on for over two years! She is very professional, understanding, patient, and kind! We are first time home buyers and she advocated for our needs and explained things to us. She even helped us find a pool vacuum! We couldn’t recommend Carrie more!”
A recent buyer client
When I would advise caution
I get cautious when the pool is the only thing carrying the home emotionally. If the roof is old, the HVAC is near the end of its life, the pool surface is tired, the enclosure is corroded, the yard drains poorly, and the seller has no records, the pool may be too expensive a distraction. You may still buy it, but the price and terms need to reflect the uncertainty.
I also get cautious when a buyer says, “We will fix that later,” about too many things at once. Later arrives quickly in Florida. Screen panels tear. Pumps fail. Roof questions show up in insurance. Heavy rain reveals drainage. A pool can be wonderful, but it is not where I want a buyer to spend their last dollar.
Bottom line for Brevard pool-home buyers
A Brevard County pool home makes the most sense when the pool is supported by a strong property file: newer or well-documented roof, clean four-point items, solid wind mitigation details, clear permits, healthy screen enclosure, safe barriers, reasonable drainage, and an insurance quote you understand.
If the house file is strong, the pool can be the thing that makes Space Coast life feel like the reason you moved here. If the house file is weak, the pool may simply make a risky purchase look prettier.
For help comparing pool homes, screened outdoor living, and lower-maintenance options, join my private Facebook group, Moving to Brevard County Florida, or reach out for a no-pressure conversation about Brevard County homes for sale with REAL Broker. I can help you separate the backyard dream from the ownership reality so your next chapter starts here.